
Global Membrane Separation Market Research
Persistence Market Research Released New Market Report on “Global Market Study on Membrane Separation: Water & Waste Water Segment to Witness Highest Growth by 2019”.
The global membrane separation market was valued at USD 19.0 billion in 2012 and is expected to grow at a CAGR of 10.8% from 2013 to 2019, to reach an estimated value of USD 39.2 billion in 2019.
Mandatory government regulation and increasing demand for clean processed drinking water is propelling the water processing industry to provide the public with clean processed drinking water free of impurities. This is providing growth opportunities for the water treatment industry.
Mandatory adherence to environmental standards such as the Clean Water Act especially in areas with water scarcity have influenced the demand for better water treatment technology, including membrane separation technology. Shifting from chemical to physical treatments is also a major driver as chemical treatments are perceived as environmentally unclean technologies with associated disposal costs. In addition, awareness of water scarcity has influenced the demand for water reuse in water stressed areas.
Worldwide industrial expansion and growing population are propelling the demand for better water treatment technology, providing growth opportunities for the global market for membrane separation technology. Additionally, the oil and petroleum industry is well established in the gulf and European countries such as Italy and Germany which use membrane separation technology for liquid separation. Expansion of such industries is expected to increase the overall demand for membrane separation technology.
Membrane separation technology is bifurcated into four major processes, microfiltration, ultrafiltration, nanofiltration and reverse osmosis. Microfiltration dominates the market with more than 35% of the global market share in 2012. Whereas water and wastewater dominates the end-user market with 36% of the global market shares in 2012. The global membrane separation market grew from USD 19.0 billion in 2010 to USD 21.2 billion in 2013.
The european membrane market (the largest in 2013) is expected to reach USD 13.8 billion in 2019, growing at a CAGR of 9.6%. In 2012 the water and wastewater sector was the major end-user of membrane separation technology and this is expected to increase at a CAGR of 11.1% during 2013-19.
The membrane separation market is fragmented with several players in the market supplying membrane separation products to the end-users (water and wastewater, industrial and healthcare) in the market. Most of the companies produce different types of membrane products such as microfiltration, nanofiltration, ultrafiltration and reverse osmosis and sell them globally.
Major companies operating globally and manufacturing all four products are Evoqua Water Technologies, Pall Corporation, Koch Membrane Systems Inc., Merck Millipore, Degremont SA, Dow Chemical Company, GEA Filtration, 3M Company, Nitto Denko Corporation and Veolia Environnement.
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
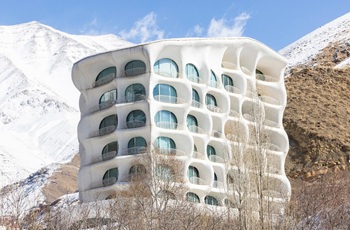
Shortlist for CIOB’s Art of Building photography competition.
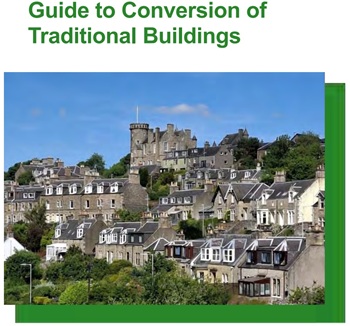
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
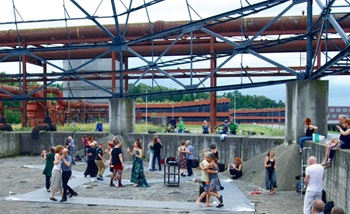
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.
Why diversity and inclusion matters for SMEs
CIOB’s D&I Charter shows how practical changes can support long-term growth.
Cut electricity bills to power growth
Coalition sends joint letter to the Chancellor.

Gasholders: a history in pictures. Book review.
Recognition, influence and growth
SocEnv identifies three strategic pillars in new strategy to 2045.
Discover the future of roofing, cladding and insulation.
New guidance for professional practice, cultural change and regulation in social housing.